What defines the scope and significance of the Oil And Gas Data Management Market?
The Oil And Gas Data Management Market encompasses the software and services required to organize vast geological and operational datasets. It is critical for managing upstream seismic data, midstream pipeline monitoring, and downstream refining logistics. By centralizing data from platforms like Schlumberger Limited or Baker Hughes Company, firms navigate complex regulatory compliance while optimizing high-stakes production cycles.
Structural Growth Drivers and Market Constraints
With a projected valuation of 81.67 Billion by 2033, growth is fueled by the need for AI-driven predictive maintenance to prevent costly facility downtime. However, the industry faces severe hurdles including geopolitical volatility and rigid OSHA or EPA compliance standards. Digital transformation, though essential, remains hampered by the high cost of migrating legacy on-premise systems to secure, cloud-native environments.
Emerging trends and digital transformation patterns
The shift toward Integrated Asset Management is redefining operational efficiency. Our analysis shows a massive pivot toward IoT-enabled real-time drilling data, which allows for dynamic adjustments during extraction. Leaders like Cognite AS and Kongsberg Gruppen are leading this charge, integrating digital twins to simulate reservoir performance, which significantly minimizes geological risk and maximizes recovery rates for global E&P operators.
How did the COVID-19 pandemic influence the market recovery trajectory?
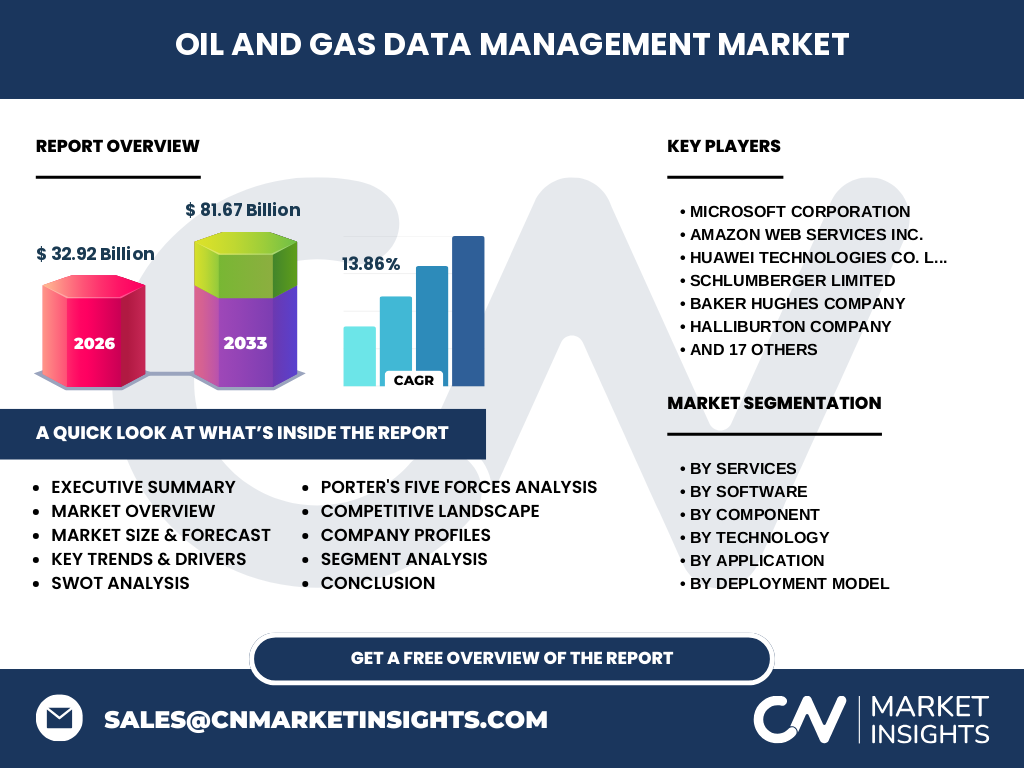
The pandemic forced a sharp focus on automation as remote site access became constrained. While initial spending slumped in 2020, the recovery trajectory accelerated as companies realized cloud-based data visibility was a survival necessity. This shift solidified the market’s current 13.86% CAGR, as firms pivoted away from manual, spreadsheet-heavy workflows toward automated, resilient digital architectures for supply chain management.
Competitive Benchmarking and Strategic Dynamics
The Oil And Gas Data Management Market is highly concentrated, with dominant tech giants like Microsoft Corporation and Amazon Web Services Inc. providing the cloud substrate for specialized software providers. Strategic differentiation is currently driven by vertical-specific capabilities, where AVEVA Group plc and Quorum Software leverage deep-domain expertise to outperform generalized IT consultancies in complex oilfield data environments.
Executive Summary: A high-level synthesis of market health
The sector is poised for exponential expansion, rising from 32.92 Billion in 2026 to 81.67 Billion by 2033. This trajectory reflects a fundamental industry transition: treating data as a high-value asset rather than a byproduct. Companies successfully integrating AI and Big Data Analytics are achieving significant reductions in CapEx, while those tethered to legacy systems face increasing competitive marginalization.
Market Forecast: What can stakeholders expect between 2027 and 2033?
Projected growth to 81.67 Billion by 2033 at a 13.86% CAGR highlights a sustained demand for sophisticated analytics. We anticipate the fastest growth within the Cloud deployment model, as downstream and midstream operators prioritize scalability. This rapid expansion is bolstered by the urgent need for decarbonization data tracking, an emerging metric that will command significant market share over the next decade.
Segmentation analysis: Breaking down services, software, and deployment
The market is segmented by Software (Integration, Analytics, Risk Compliance), Services (Consulting, Managed, Migration), and Technology (AI, IoT). Risk and Compliance Management Software is currently the fastest-growing sub-segment, driven by global mandates. Meanwhile, Managed Services are gaining traction as companies offload the burden of maintaining complex database management systems to specialized service providers like Infosys Limited or Wipro Limited.
Regional market analysis and geographic performance
North America retains the largest share due to the density of shale play operations and technological maturity. However, the Middle East and APAC regions are rapidly adopting digital oilfield technologies to modernize aging infrastructure. Localized constraints, such as port logistics in the Gulf of Mexico versus remote arctic drilling in Norway, dictate the specific software tools adopted by local E&P players.
In-depth review of key regional market dynamics
In North America, high labor costs drive the adoption of automation and AI. Conversely, in the Middle East, the focus remains on Production Data Management to extend the life of mature fields. European markets, governed by stricter environmental data reporting requirements (e.g., EU Taxonomy), are leading the adoption of advanced Risk and Compliance Management Software to ensure regulatory compliance across downstream distribution networks.
Company profiles and strategic positioning
Leading players occupy distinct strategic niches. Palantir Technologies Inc. excels in high-level operational intelligence for upstream, while Aspen Technology Inc. dominates downstream simulation. Katalyst Data Management Inc. provides critical specialized support for seismic data archiving. These companies compete by creating integrated ecosystems, ensuring that data flows seamlessly from geological exploration models directly into executive-level decision dashboards.
Porter's Five Forces analysis of the current market
The threat of new entrants is moderate, mitigated by high barriers to entry related to proprietary industry knowledge and deep technical integration. Buyer power remains significant, as large E&P companies dictate terms. However, the threat of substitutes is low, as the reliance on specialized big data analytics for complex hydrocarbon recovery is now an irreversible industry standard.
SWOT analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths: Deep domain expertise and high entry barriers. Weaknesses: High legacy debt in data infrastructure. Opportunities: Leveraging AI/ML for carbon capture verification and energy transition metrics. Threats: Severe cybersecurity risks targeting critical infrastructure and volatile energy pricing which can lead to sudden budget freezes in capital-intensive software projects. Managing these factors is essential for sustained growth.
Value chain analysis: From raw data to end-user value
The value chain initiates at the wellhead and seismic sensor, where raw data is captured. It flows through data integration layers provided by companies like Petrosys Pty Ltd, then to analytics platforms. The end-users—ranging from drilling engineers to refinery managers—derive actionable value, enabling cost optimization, improved safety, and streamlined regulatory reporting for oil and gas industry operators.
Investment insights and strategic recommendations
Investors should prioritize companies offering end-to-end cloud-native platforms. High-potential areas include ESG data management and autonomous rig operation software. Strategic partnerships with firms that can bridge the gap between OT (Operational Technology) and IT are particularly valuable, as these entities are currently best-positioned to capture the most significant share of the 81.67 Billion market projection by 2033.
Conclusion and key takeaways for stakeholders
The Oil And Gas Data Management Market is at an inflection point. With a projected 13.86% CAGR, the industry is moving toward a fully digitized future. Success will be defined by the ability to harmonize legacy assets with modern AI capabilities. Stakeholders should focus on scalability and security, as these will be the primary determinants of market leadership through the 2033 forecast period.
Research methodology and data triangulation
Our research employs a triangulation methodology, combining proprietary primary stakeholder interviews with global trade registry data and macroeconomic indicators. We cross-reference SEC filings of major players like Halliburton Company and Emerson Electric Co. with industry-specific energy consumption data to validate our growth estimates, ensuring that the 32.92 Billion baseline and 2033 forecast remain rigorous and defensible.
Scope of the report: Parameters and limitations
This report covers global spending on software and services related to upstream, midstream, and downstream data management. It excludes generic IT hardware sales to focus strictly on industry-specialized applications. While our analysis accounts for technological and economic trends, limitations include unpredictable shifts in global geopolitical policy and sudden changes in fossil fuel regulatory regimes which could impact specific regional adoption rates.
Recent developments, partnerships, and market moves
Recent strategic moves emphasize cloud consolidation and AI partnership ecosystems. Companies like PetroAI Inc. are gaining visibility through innovative AI drilling algorithms. Furthermore, major alliances between hyperscale cloud providers and industry leaders demonstrate a move toward as-a-service models. These partnerships are instrumental in lowering the barrier for mid-sized producers to access enterprise-grade data management tools, effectively expanding the addressable market.